

By now, you should have a pretty good idea about how much your garage will cost.
You know:
- The cost of the prefab garage you want, including installation
- The cost of permits
- The cost of a concrete foundation for your garage
Once you total those up, you’ll know the total cost of your project and how much financing you may need (if any). If you’ve got the cash you need to pay for everything, you just need to order your garage to get started. You only need to pay us a deposit when you order, which is usually between 10% and 20% of the total. The balance isn’t due until after the garage is installed (unless you are ordering a very large garage over $15,000, in which case 50% of the balance is due when your installation is scheduled). You can pay both amounts with any major credit card.
If you need a way to finance your garage, here are some options:
We don’t lend in-house. That keeps pricing simple: you arrange financing with a lender, funds go to you, and you pay us like a cash customer. Delivery and installation are included.
You can check HFS Financing, Acorn Finance, or both. Checking a rate or pre-qualified offers is a soft inquiry and should not affect your credit score.
Via HFS Financial · no impact to check a rate · we are not the lender
via Acorn Finance · no impact to check a rate · we are not the lender
Personal Loan
You don’t need home equity, an appraisal, or a refinance to get started. Check a metal garage loan through HFS Financial in about a minute.
If you’re approved, the money comes to you. Place a refundable deposit with us to lock today’s price, then pay the rest after installation like a cash customer.
Why customers use HFS
- No home equity, no appraisal, and no lien on your house
- Terms up to 30 years, so the monthly payment can stay lower
- Loan amounts from a few thousand dollars up to $300,000
- Credit often considered in the low 600s
- Can cover the building plus extras like a slab or permits
- No prepayment penalty if you want to pay it off early
- Funds go to you, not to Alan’s Factory Outlet
Example only, not a quote: about $181 a month for a $15,000 loan at 7.8% over 10 years. Your rate and payment depend on credit, income, and the lender you match with.
How it works with us

Design your building and place a refundable deposit to lock the price.

If approved, funds go to your account.

Pay the remaining balance after installation. Larger buildings may need a payment when installation is scheduled.
This is not an Alan’s Factory Outlet loan. A third-party lender sets the approval, rate, and fees.
A good fit if you own a primary or secondary home in your name and want a metal garage, carport, or workshop for personal use.
Vacant land, commercial use, or property held in an LLC or trust usually needs a different option.
Good to know
- Advertised rates starting in the mid-7% are for well-qualified borrowers. Many people pay more.
- A longer term lowers the monthly payment but costs more interest. You can pay extra anytime.
- HFS is a loan marketplace. The first estimate can change after underwriting.
- Approval is not guaranteed.
HFS Financial is not a lender (NMLS / MD CSB #1680766). Alan’s Factory Outlet is not a lender and does not approve loans. Rates, fees, and terms are set by unaffiliated third-party lenders, subject to credit approval, and can change.
Print or save a 2-page summary:
Acorn Finance — compare personal loan offers
Acorn Finance partners with a network of lenders so you can search personal loan offers and break the project into monthly payments.
Why customers use Acorn
- No impact to your credit score when checking pre-qualified offers
- Loan amounts from $1,000 to $100,000 with competitive APRs
- Terms from 2–20 years to help spread out your payments
- If approved, you could get funded in as soon as 24 hours
- Funds go to you, then pay us like a cash customer
How it works with us
Check pre-qualified offers (soft pull).

If you’re pre-qualified, choose an offer and apply for final approval with the lender.
Once approved, you could get funded in as soon as 24 hours. Use those funds to pay your project costs.
If you apply for a specific offer, the lender will conduct a hard credit pull, and this could impact your credit score. Funding times may vary.
Print or save a 1-page summary:
Vacant land, commercial use, or property held in an LLC or trust usually needs a different option. See HELOC and other choices below, or contact us.
Good to know
- Advertised HFS rates starting in the mid-7% are for well-qualified borrowers. Many people pay more.
- A longer term lowers the monthly payment but costs more interest. You can pay extra anytime.
- HFS and Acorn are loan marketplaces. The first estimate or pre-qualified offer can change after underwriting.
- Approval is not guaranteed. Funding times may vary.
HFS Financial is not a lender (NMLS / MD CSB #1680766). Acorn Finance is not a lender; it partners with lenders to make loans available. Alan’s Factory Outlet is not a lender and does not approve loans. Rates, fees, and terms are set by unaffiliated third-party lenders, subject to credit approval, and can change. Prequalifications use a soft credit pull that does not impact your credit score. If you express interest in a specific offer, the funding partner will conduct a hard credit pull, and this could impact your credit score.
Second Mortgage or Home Equity Line of Credit (HELOC). If you’ve been paying off your mortgage or your house is worth more than what you paid for it, you probably qualify for a second mortgage or a line of credit on your house. Like your primary mortgage, these types of loans are secured by the value of your home.
As a result, the interest rate is usually very reasonable. A second mortgage is good for a one-time purchase. A HELOC is a line of credit that you can use again and again as needed. The line of credit will give you more flexibility for your project, and you can also use it for other large purchases or emergencies in the future. Some HELOCs are much more flexible than others, and rates vary, so it pays to shop around at local banks. If a bank turns you down due to insufficient income or equity, a local credit union might still consider giving you a loan. However, be prepared for extensive paperwork and some waiting time while your loan is processed and approved.
Zero-Interest Card. If you know you’ll be able to pay off the total in less than two years, a zero-interest credit card may be an option. Some cards don’t charge interest for up to 21 months. But you’ll need to check the terms carefully and make sure that your credit limit will be large enough to cover the necessary expenses.
Cash-Out Refinance. If you have a high interest rate on your mortgage, a cash-out refinance could provide the funds you need for your garage and lower your interest rate. You might even be able to lower your mortgage payments. Remember that you’ll have to pay closing fees though, which can be expensive.
Place Your Order
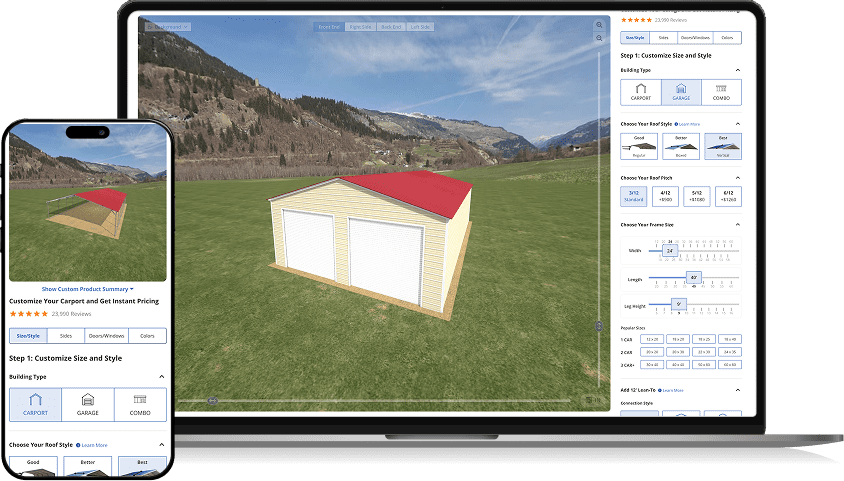
Once your financing is in place, you’re ready to order. If you’ve saved your design, locate the email with your design link and open it in the online designer. If you can’t find your saved design or want to start from scratch, visit the 3D Garage Builder on our website.
Once you have everything the way you want it, place your order and pay the deposit to lock in your price.
After you place your order, my team will send you information about requesting a permit and getting your site ready for installation. Then we will hold your order until your permit is issued and your site is ready. Once you have everything ready, we’ll notify the manufacturer, and your order will be put in a queue for scheduling. If you need to make customizations to your design that aren’t possible with the 3D Garage Builder, just give me a call at 1-800-488-6903.
In the next chapter, I’ll walk you step by step through the process of getting your permit.